
How Compound Interest Works for CPF, Fixed Deposits and SSBs
How compound interest grows CPF savings at 2.5%, 4% and 5%, why CPF compounds yearly, and how fixed deposits, savings accounts and Savings Bonds compare in S$.
By Redbison Dev · · 6 min read
Singapore edition. Written for Singapore savers: CPF's 2.5% and 4% base rates for October to December 2026 and extra interest, CPF's yearly compounding, fixed deposits and savings accounts, Singapore Savings Bonds, SDIC cover and the IRAS treatment of interest. US edition
For most people in Singapore, the compound interest that matters most is CPF. For 1 October to 31 December 2026 the Ordinary Account (OA) pays 2.5% a year and the Special, MediSave and Retirement Accounts pay 4%, and CPF Board says interest is computed monthly, credited by the following year and compounded annually. Left alone for 10 years, S$20,000 grows to S$25,601.69 at the OA rate and S$29,604.89 at 4%. The Singapore Compound Interest Calculator opens on that S$20,000 with yearly compounding. This guide shows how the formula works on CPF balances, what extra interest adds, how monthly top-ups grow, and how bank deposits and Singapore Savings Bonds fit in. It explains the maths and is not advice on CPF transfers or any product.
The formula, with CPF's numbers
Compound interest pays interest on earlier interest. With annual compounding the balance after t years is:
A = P x (1 + r)^t
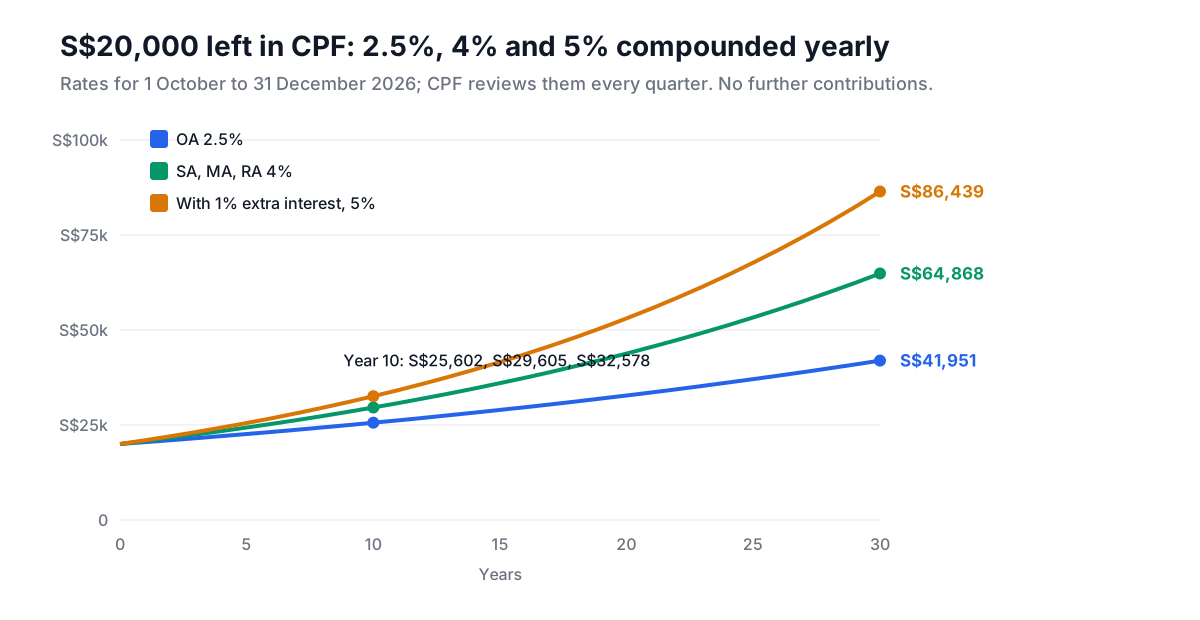
For S$20,000 at 4% for 10 years, A = 20,000 x 1.04^10 = S$29,604.89, of which S$9,604.89 is interest. At 2.5% the same S$20,000 earns S$5,601.69. Over longer periods the gap widens because each year's interest earns interest too:
| Years | OA 2.5% | SA, MA, RA 4% | 5% with extra interest |
|---|---|---|---|
| 10 | S$25,601.69 | S$29,604.89 | S$32,577.89 |
| 30 | S$41,951.35 | S$64,867.95 | S$86,438.85 |
Why CPF compounds yearly
CPF Board says interest is computed monthly but credited by the following year and compounded annually, so interest earned in March only starts earning interest of its own the next year. Contributions that arrive in a month start earning from the following month, and withdrawals stop earning from the month they are made. In the calculator, choose annual compounding for CPF. A bank that credits interest monthly compounds monthly; choose that for a savings account.
Where the rates come from
CPF reviews both rates every quarter. The OA rate follows the three-month average of major local banks' interest rates, with a legislated minimum of 2.5%. The SA, MediSave and RA rate follows the 12-month average yield of 10-year Singapore Government Securities plus 1%, with a 4% floor that the Government has extended to 31 December 2027. Because the rates can change each quarter, every figure above is an illustration at today's base rates, not a promise.
Extra interest on the first S$60,000
The Government pays extra interest on the first S$60,000 of combined CPF balances, with the OA counted only up to S$20,000. CPF says savings can earn up to 5% a year, or 6% for members aged 55 and above. Extra interest earned on OA savings is paid into the SA or RA, not back into the OA.
Example, one year for a member with S$40,000 in the OA and S$20,000 in the SA. Ignoring the monthly timing:
- OA base interest: 2.5% of S$40,000 = S$1,000
- SA base interest: 4% of S$20,000 = S$800
- extra 1% on the first S$60,000, counting only S$20,000 of the OA: 1% of S$20,000 (OA) + 1% of S$20,000 (SA) = S$400, all paid into the SA
That is S$2,200 for the year. The extra interest counts only the first S$20,000 of the OA, so the other S$20,000 earns the base 2.5% alone.
Monthly contributions
Regular saving is where compounding becomes visible. CPF's own guide says S$100 a month from age 25 at 4% grows to over S$116,000 by 65. The calculator brackets that figure:
- annual compounding, contributions credited at year end: S$114,030.62
- monthly compounding: S$118,196.13
- paid in: S$48,000
CPF's figure sits between the two because CPF computes interest monthly but adds it once a year. The same guide says that starting at 35 instead needs about S$170 a month to reach a similar sum; the calculator gives S$114,413.27 with annual compounding and S$117,988.40 monthly, from S$61,200 paid in. Ten years later costs S$13,200 more of your own money for about the same result.
CPF's guide also notes that the second S$100,000 comes faster than the first. Saving S$10,000 at the end of each year at 4%, the balance passes S$100,000 after the 9th deposit (S$105,827.95) and S$200,000 after the 15th (S$200,235.88): six years for the second S$100,000, as CPF says.
The rule of 72
Divide 72 by the rate for a rough doubling time. At 4% that is 18 years, and the calculator gives S$10,000 growing to S$20,258.17 after 18 years. At the OA's 2.5% it is about 29 years (S$20,464.07).
Bank deposits and Savings Bonds
The same formula applies outside CPF, with the bank's or MAS's numbers:
- Fixed deposits pay a fixed rate for a fixed term. S$50,000 for three years at an illustrative 3%, compounded annually, grows to S$54,636.35. A one-year deposit that pays its interest at maturity is simple interest.
- Savings accounts that credit monthly compound monthly. S$20,000 at 2% a year grows to S$22,101.58 over five years with monthly crediting against S$22,081.62 yearly, a S$19.96 difference. Frequency matters much less than the rate.
- Singapore Savings Bonds step their coupons up each year. MAS sets each issue so that the average annual compounded return over a holding period is linked to the Singapore Government Securities yield of the same tenor, so enter that average return with annual compounding. They can be redeemed in any month without penalty.
Deposits with a Deposit Insurance Scheme member bank or finance company are insured by SDIC up to S$100,000 per depositor per member. IRAS lists interest on deposits with approved banks and licensed finance companies in Singapore, and on bonds held by an individual outside a partnership or trading business, as not taxable, so the interest shown is the interest you keep. Inflation is not in these figures; at 2.5% interest and 2.5% inflation the buying power of the OA balance stands still.
Mistakes that throw the numbers off
- Using monthly compounding for CPF. It overstates the balance slightly: S$118,196.13 against S$114,030.62 over 40 years of S$100 a month.
- Assuming today's rate for 40 years. CPF rates are reviewed quarterly; the floors are what is guaranteed, and the 4% floor is extended only to the end of 2027.
- Counting the whole OA for extra interest. Only the first S$20,000 of the OA counts towards the S$60,000.
- Comparing a bonus savings rate with a fixed deposit without checking the cap. If a bonus rate applies only to part of the balance, enter the blended rate you will actually earn.
Tools for this job
- Compound Interest Calculator (Singapore): CPF, fixed deposits and savings in S$, with top-ups and a year-by-year table.
- Interest Calculator (Singapore): simple and compound interest for fixed deposits, savings accounts and Savings Bonds.
- Inflation Calculator: what a future balance would buy at current prices.
The original compound interest guide covers APY against APR and debt that compounds against you.
Frequently asked questions
How does CPF interest compound?
CPF Board says interest is computed monthly, credited by the following year and compounded annually. Contributions earn from the month after they arrive. Use annual compounding in the calculator.
How much will S$20,000 in my CPF SA grow to?
At the 4% base rate, compounded yearly, S$29,604.89 after 10 years and S$64,867.95 after 30, if the rate stayed at 4% and nothing more was added. In the OA at 2.5% it would be S$25,601.69 and S$41,951.35.
Who gets 5% or 6% on CPF savings?
Extra interest of 1% a year is paid on the first S$60,000 of combined balances, with the OA counted up to S$20,000, so those savings can earn up to 5%. CPF says members aged 55 and above can earn up to 6%.
Is interest on fixed deposits taxed in Singapore?
IRAS lists interest on deposits with approved banks and licensed finance companies in Singapore as not taxable for individuals. Deposits with SDIC members are also insured up to S$100,000 per depositor per member.
How long does money take to double at CPF rates?
About 18 years at 4% and 29 years at 2.5%, by the rule of 72. The calculator confirms S$10,000 at 4% reaches S$20,258.17 after 18 years.
Sources and further reading
- Earning CPF interest, CPF Board. Rates for 1 October to 31 December 2026, how they are set, the 4% floor to 2027 and extra interest.
- How is my CPF interest computed and credited?, CPF Board. Computed monthly, credited by the following year, compounded annually.
- Multiplying your CPF savings with compound interest, CPF Board. S$100 a month from 25, S$170 from 35, the second S$100,000 and the rule of 72.
- Singapore Savings Bonds, Monetary Authority of Singapore. Step-up coupons and the average annual compounded return.
- Deposit Insurance Scheme, Singapore Deposit Insurance Corporation. Cover up to S$100,000 per depositor per member.
- Interest, IRAS. Interest from approved banks and licensed finance companies is not taxable.
Open the Compound Interest Calculator
More Calculators
Every tool in the Calculators section, free and in your browser.
- Investment Calculator
- Compound Interest Calculator
- Simple Interest Calculator
- Interest Calculator
- EMI Calculator
- Retirement Calculator
- Time-Weighted Return Calculator
- Savings Goal Calculator
- Inflation Calculator
- CAGR Calculator
- ROI Calculator
- Present and Future Value Calculator
- NPV and IRR Calculator
- 401(k) Calculator
- Roth IRA Calculator
- APY and CD Calculator
- SIP Calculator
- Annuity Calculator
- Bond Price and Yield Calculator
- Currency Converter
- Dividend Calculator
- Stock Average Calculator
- RMD Calculator